Headline: International Trade Finance With SBLC: Complete Guide
International trade finance with SBLC has become an important financing and risk-management option for companies conducting cross-border business. Importers, exporters, commodity traders, contractors, manufacturers, and project developers often need a reliable financial instrument that can support commercial obligations without requiring immediate cash payment.
A Standby Letter of Credit (SBLC) can provide that support when the transaction structure, issuing bank, beneficiary requirements, documentation, and applicable rules align.
International trade creates a fundamental timing problem. An exporter wants confidence that it’ll receive payment, while an importer wants assurance that it won’t release funds without meeting agreed contractual conditions. Trade finance helps manage this gap through credit, guarantees, insurance, documentary credits, and related financial instruments. The World Trade Organization notes that approximately 80–90% of world trade relies on trade finance, including trade credit, insurance, and guarantees.
For businesses evaluating SBLC trade finance, understanding how the instrument works matters more than simply obtaining an SBLC. The commercial transaction should come first. The financial instrument should then support that transaction.
Keywords: international trade finance with SBLC, SBLC trade finance, international trade finance, SBLC financing, standby letter of credit, international SBLC provider, SBLC for international trade, trade finance solutions, SBLC-backed financing, international trade finance solutions, SBLC payment guarantee, SBLC credit enhancement, global trade finance, standby letter of credit financing
What Is International Trade Finance With SBLC?
International trade finance refers to financial structures that facilitate transactions between buyers and sellers operating across different countries.
These structures can address:
- Payment risk
- Counterparty risk
- Working-capital requirements
- Supplier financing
- Import financing
- Export financing
- Contractual obligations
- Credit enhancement
- Cross-border settlement
- Performance requirements
An SBLC, or Standby Letter of Credit, is an undertaking issued by a bank or other eligible financial institution for the benefit of a named beneficiary.
Under an SBLC structure, the issuer undertakes to make payment if the beneficiary makes a complying presentation under the terms of the standby.
The ICC describes an SBLC as an independent undertaking that provides assurance of payment from its issuer. The instrument supplements the underlying commercial agreement rather than replacing it.
That distinction matters.
An SBLC isn’t simply a loan. It isn’t automatically cash. It doesn’t guarantee that every financing institution will accept it as collateral.
Instead, it can provide financial assurance, strengthen a transaction structure, and, where a financing institution accepts the instrument, support a broader financing arrangement.
For companies searching for international trade finance solutions with SBLC, the first question should therefore be:
What commercial obligation does the SBLC need to support?
Once that question has a clear answer, the appropriate structure becomes easier to evaluate.
Why SBLCs Matter in Cross-Border Trade
International transactions involve more variables than domestic transactions.
The buyer and seller may operate under different legal systems. They may use different currencies. Their banks may follow different procedures. They may also face different regulatory, political, logistical, and credit environments.
Trade finance addresses these issues by introducing structured financial commitments between the parties.
An SBLC can help a beneficiary gain additional payment assurance without requiring the applicant to make an immediate cash payment.
For example, an importer purchasing equipment from an overseas manufacturer may need the supplier to accept deferred payment terms. The supplier may agree if a qualifying bank provides an SBLC supporting the buyer’s payment obligation.
This arrangement can help both parties manage liquidity.
The buyer preserves working capital according to the agreed transaction structure, while the seller receives additional assurance from the issuing institution.
The WTO similarly identifies payment risk, delivery risk, and liquidity risk as important challenges within international trade.
Key Benefits of SBLC Trade Finance
A properly structured SBLC may support:
- Payment assurance
- Supplier confidence
- Credit enhancement
- Cross-border commercial transactions
- Working-capital structures
- Contractual financial obligations
- International procurement
- Project-related financing
- Trade-related liquidity arrangements
- Risk allocation between counterparties
However, these benefits depend on the actual instrument, issuer, beneficiary, governing rules, transaction documents, and financing institution.
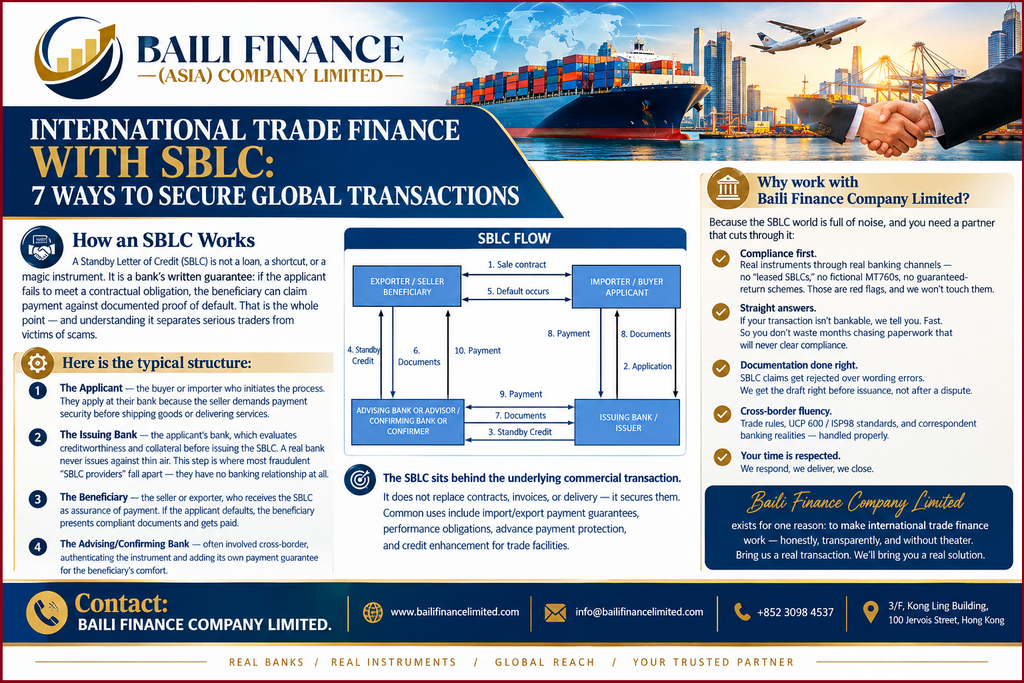
How an SBLC Works in International Trade Finance
Although individual transactions differ, the basic process usually involves several parties.
1. Applicant
The applicant requests the SBLC.
This may be an importer, trading company, contractor, project company, manufacturer, or other commercial entity.
The applicant normally provides corporate information, transaction documents, financial information, identification documents, and details about the intended beneficiary.
2. Issuing Bank
The issuing bank issues the SBLC on behalf of the applicant.
The bank evaluates the applicant according to its own credit, compliance, legal, and risk requirements.
3. Beneficiary
The beneficiary receives the benefit of the undertaking.
Depending on the transaction, the beneficiary may be an exporter, supplier, contractor, lender, project counterparty, or another commercial party.
4. Advising or Confirming Bank
An advising bank may authenticate and advise the instrument to the beneficiary.
In certain structures, another bank may provide confirmation, creating an additional undertaking subject to the applicable terms.
5. Financing Institution
Where the SBLC forms part of a financing structure, a financing institution may assess whether it can accept the instrument as credit support.
This assessment is separate from the mere issuance of the SBLC.
SBLC vs Letter of Credit: What’s the Difference?
Businesses often confuse an SBLC with a documentary letter of credit.
They serve different commercial purposes.
A commercial Letter of Credit (LC) generally supports payment against stipulated documents relating to an underlying trade transaction.
An SBLC generally functions as a secondary payment undertaking or financial assurance that becomes relevant when the applicant doesn’t meet an obligation specified in the standby.
The ICC explains that standby credits have similarities to commercial documentary credits but require different practices because of their distinct scope and use. ISP98 was developed specifically to provide a detailed framework for standby letters of credit.
| Feature | SBLC | Commercial LC |
|---|---|---|
| Primary purpose | Backup assurance or defined payment undertaking | Payment mechanism for trade |
| Typical trigger | Failure or specified event under the standby | Complying presentation under LC terms |
| Common use | Payment security, credit enhancement, contractual obligations | Import and export transactions |
| Governing rules | Often ISP98 or UCP 600, depending on structure | Commonly UCP 600 |
| Role in financing | May support financing where accepted | Often directly facilitates trade settlement |
| Documentation | Defined by the standby | Typically extensive trade documents |
The correct instrument depends on the transaction.
ISP98 and the Rules Governing SBLCs
The governing rules deserve careful attention.
ISP98 — International Standby Practices 1998 — provides a specialized framework for standby letters of credit. The ICC has endorsed ISP98 and publishes it as ICC Publication No. 590.
ISP98 addresses important areas including:
- Obligations
- Presentation
- Examination
- Notice
- Cancellation
- Reimbursement
- Timing
- Transfer
- Syndication and participation
The ICC states that ISP98 provides a precise framework for practitioners dealing with standby letters of credit.
For businesses researching ISP98 SBLC trade finance, this is particularly relevant because the wording of an instrument determines how the parties should interpret presentation requirements, expiry provisions, demands, and other obligations.
The rules don’t replace the need for proper drafting.
They provide a framework within which the instrument operates.
Businesses should therefore review the proposed SBLC wording carefully before issuance.
UCP 600 and SBLCs
UCP 600 is primarily associated with documentary credits.
An SBLC may also incorporate UCP 600, depending on the transaction structure and the parties’ agreement.
The appropriate governing rules should therefore be selected deliberately rather than inserted into an instrument without considering its intended function.
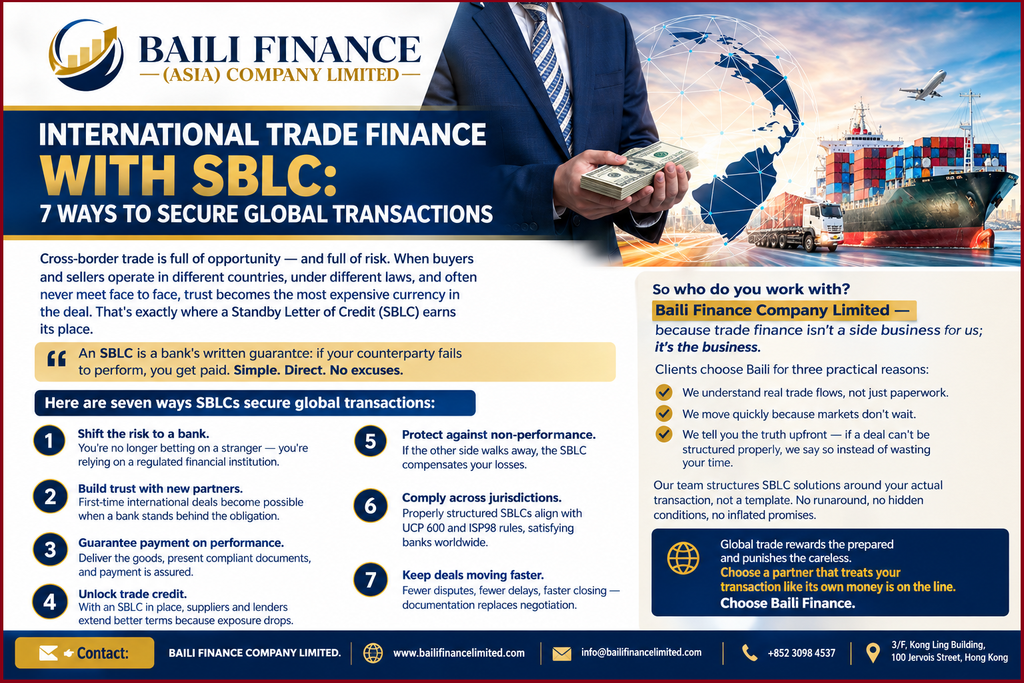
7 Ways SBLCs Can Support International Trade Finance
1. Payment Security
An SBLC can provide a beneficiary with an additional source of payment assurance.
For example, an exporter may agree to ship goods on credit terms because a bank-backed undertaking supports the buyer’s obligation.
2. Supplier Confidence
A supplier may hesitate to enter a large transaction with a new international buyer.
An acceptable SBLC can provide additional assurance and help the parties negotiate commercial terms.
3. Credit Enhancement
A bank-issued undertaking can strengthen the financial structure of a transaction when an acceptable financing institution recognizes the issuer and the instrument.
This can be relevant when the applicant’s standalone credit profile doesn’t satisfy the counterparty’s requirements.
4. Working Capital
An SBLC may form part of a broader working-capital structure.
However, businesses shouldn’t assume that an SBLC automatically converts into working capital.
The financing institution must assess the instrument, issuer, applicant, transaction, repayment source, jurisdiction, and other relevant factors.
5. Import and Export Transactions
Importers can use structured financial instruments to satisfy supplier requirements while managing payment timing.
Exporters, meanwhile, can obtain additional payment assurance before releasing goods.
6. Project and Contract Finance
SBLCs can also support defined contractual or financial obligations associated with large commercial projects.
Depending on the agreement, the beneficiary may require a financial undertaking before commencing performance.
7. Cross-Border Risk Management
An SBLC can form part of a broader risk-management strategy.
It doesn’t eliminate commercial risk. Instead, it can allocate a specific financial risk to the issuing institution according to the terms of the undertaking.
Real-World Example: $5 Million Equipment Transaction
Consider an international equipment transaction involving a buyer in Oman and an established manufacturer in China.
The buyer wants to purchase industrial equipment valued at US$5 million.
The supplier is prepared to manufacture and ship the equipment, but it doesn’t want to accept the buyer’s payment promise without additional financial assurance.
The parties agree that an SBLC can support the buyer’s payment obligation.
Transaction Structure
The buyer approaches a suitable financial provider and begins the required due diligence.
The transaction team reviews:
- Purchase agreement
- Buyer information
- Supplier information
- Transaction value
- Currency
- Beneficiary details
- Payment terms
- SBLC wording
- Expiry date
- Governing rules
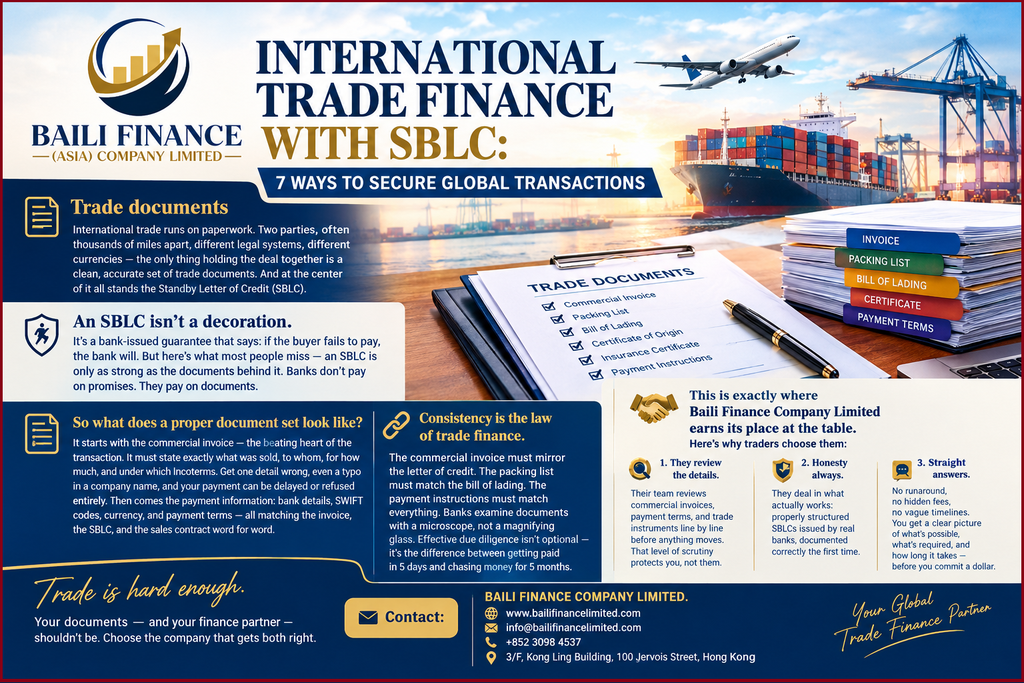
- Required presentation documents
- Banking requirements
- KYC and AML information
If the transaction receives the necessary approvals, an issuing bank can issue the SBLC according to the agreed terms.
The beneficiary’s bank receives and authenticates the instrument through the applicable banking channel.
The supplier can then assess the financial assurance against its own acceptance criteria.
If the buyer performs its contractual obligations, the standby may never be drawn.
If a defined default occurs and the beneficiary presents documents that comply with the SBLC requirements before expiry, the issuing bank evaluates the presentation under the applicable rules.
This illustrates an important principle:
The SBLC supports the transaction; it doesn’t replace the transaction.
Case Study: Structuring SBLC Support for an Importer
Consider a hypothetical manufacturing company importing production equipment from Europe.
The company has a viable purchase contract but wants to preserve working capital for installation, staffing, logistics, and operating expenses.
The European supplier requires payment protection before releasing the equipment.
The Challenge
The importer needs:
- US$3 million of equipment
- 180-day payment terms
- Additional supplier assurance
- A defined payment-security mechanism
- Cross-border banking support
Paying the entire purchase price upfront would place pressure on the importer’s working capital.
The Proposed Structure
The parties agree to evaluate an SBLC supporting the importer’s payment obligation.
The financial review covers the applicant, transaction documents, beneficiary, issuing institution, instrument wording, jurisdiction, and repayment source.
The SBLC is then structured around the underlying contract.
The Result
The commercial objective becomes clearer.
The supplier receives a bank-backed undertaking subject to the agreed terms, while the importer retains the payment timetable established by the transaction.
The financing institution, however, still needs to determine whether it accepts the structure.
This distinction protects the transaction from a common misunderstanding: having an SBLC isn’t the same as having guaranteed financing.
A legitimate trade-finance structure requires due diligence, appropriate documentation, bank acceptance, compliance procedures, and commercially credible repayment arrangements.
What Businesses Should Check Before Using an SBLC
Before entering an SBLC transaction, conduct a structured review.
Verify the Issuing Institution
The identity and credit quality of the issuer matter.
A beneficiary or financing institution may reject an instrument from an issuer that doesn’t meet its requirements.
Review the SBLC Wording
Read the instrument carefully.
Check:
- Amount
- Currency
- Applicant
- Beneficiary
- Issuing bank
- Expiry
- Place of presentation
- Presentation requirements
- Governing rules
- Applicable law
- Payment conditions
- Amendment provisions
Small drafting differences can produce significant practical consequences.
Confirm the Commercial Purpose
An SBLC should have a legitimate commercial reason.
Be precise about whether the instrument supports:
- Import finance
- Export finance
- Supplier payment
- Project finance
- Contractual performance
- Credit enhancement
- Working capital
- Other defined obligations
Review All Costs
Businesses should understand every applicable cost before committing.
Potential costs may include:
- Issuance fees
- Bank charges
- Advising fees
- Confirmation fees
- Legal costs
- Due diligence costs
- Financing costs
- Arrangement fees
- Amendment charges
A transparent transaction should clearly identify the relevant costs.
Conduct KYC and AML Checks
Cross-border financial transactions require appropriate compliance procedures.
Businesses should expect legitimate financial counterparties to request corporate, ownership, identification, financial, and transaction information.
SBLC Monetization and Trade Finance
SBLC monetization refers to financing structures in which an eligible SBLC may be used as credit support for financing.
This area requires particular caution.
An SBLC isn’t automatically monetizable.
The financing institution may consider:
- Issuing bank
- Credit standing
- SBLC amount
- Currency
- Expiry
- Governing rules
- Instrument wording
- Beneficiary
- Applicant
- Jurisdiction
- Transaction purpose
- Financing structure
- Repayment source
The financier also needs to establish whether the instrument is authentic, enforceable, transferable where relevant, and acceptable under its internal policies.
Therefore, businesses searching for SBLC monetization for international trade finance should avoid providers that promise unconditional funding without reviewing the underlying transaction.
A professional assessment should come before financial commitment.
How to Evaluate an SBLC Provider
Selecting an SBLC provider requires more than comparing advertised pricing.
Consider the following:
Banking Relationships
Ask which financial institution will issue the instrument and whether the proposed beneficiary or financier accepts that institution.
Transaction Transparency
The provider should explain the process, documentation, fees, expected timelines, and responsibilities of each party.
Compliance
The transaction should accommodate KYC, AML, sanctions screening, and applicable legal requirements.
Instrument Terms
Review the actual proposed wording rather than relying solely on marketing descriptions.
Commercial Purpose
A provider should understand what the instrument is intended to accomplish.
Independent Verification
Where appropriate, obtain independent legal, banking, and financial advice before signing or transferring funds.
For businesses considering a Hong Kong SBLC provider, Baili Finance states that it provides SBLC, bank guarantee, trade finance, and structured finance services from Hong Kong. Its published company information identifies BAILI FINANCE (ASIA) COMPANY LIMITED as a Hong Kong-registered company.
Those claims should still be independently verified as part of any prospective transaction.
Common Mistakes in SBLC Trade Finance
Several mistakes can create unnecessary financial and operational risk.
Treating an SBLC as Automatic Cash
An SBLC provides an undertaking under specified conditions. It doesn’t automatically create unrestricted liquidity.
Ignoring the Beneficiary’s Requirements
The beneficiary may have specific requirements concerning the issuing bank, wording, governing rules, amount, expiry, and presentation.
Using Generic Templates
A template doesn’t necessarily fit a particular transaction.
The instrument should reflect the underlying commercial obligation.
Focusing Only on Fees
The lowest quoted fee doesn’t necessarily produce the most appropriate structure.
Issuer acceptability, legal terms, documentation, compliance, and financing compatibility matter.
Skipping Independent Verification
Before transferring significant funds or signing complex documentation, obtain appropriate independent professional advice.
International Trade Finance With SBLC in Emerging Markets
Trade finance can be particularly important for companies operating in emerging markets.
The WTO and IFC have examined trade-finance conditions in West Africa, including Ghana, Côte d’Ivoire, Nigeria, and Senegal. Their research identifies persistent challenges in access to trade finance across developing economies.
For businesses in these markets, structured financial instruments can become relevant when suppliers require stronger payment assurance or when traditional financing doesn’t fully match the transaction.
However, international trade finance still requires disciplined documentation.
The instrument must fit the transaction.
The issuing bank must be acceptable.
The financing structure must be commercially viable.
And the parties must understand their obligations.
A Practical SBLC Trade Finance Checklist
Before proceeding, ask these questions:
- What is the underlying transaction?
- Who is the applicant?
- Who is the beneficiary?
- What amount is required?
- What currency will the SBLC use?
- Which bank will issue it?
- Will the beneficiary accept that bank?
- Which rules will govern the instrument?
- What is the expiry date?
- What documents are required for a claim?
- Is confirmation required?
- Is financing required?
- Will the proposed financier accept the SBLC?
- What is the repayment source?
- What are the total costs?
- Has independent due diligence been completed?
- Are KYC and AML requirements satisfied?
- Has qualified legal advice been obtained where appropriate?
If these questions don’t have clear answers, the transaction needs further review before commitment.
Frequently Asked Questions About International Trade Finance With SBLC
1. What is an SBLC in international trade finance?
An SBLC is a bank-issued undertaking that provides a beneficiary with payment assurance if the applicant fails to meet a specified obligation and the beneficiary makes a complying presentation under the standby’s terms.
2. Can an SBLC be used for import and export finance?
Yes, an SBLC can support certain import and export transactions, particularly where a supplier requires additional payment assurance. The precise structure depends on the underlying contract and the requirements of the banks and counterparties involved.
3. Is an SBLC the same as a Letter of Credit?
No. A commercial LC generally functions as a primary payment mechanism against compliant documents, while an SBLC commonly provides a secondary or standby undertaking. The precise obligations depend on the instrument wording and governing rules.
4. What rules govern an SBLC?
ISP98 is a specialized framework for standby letters of credit. Some standby transactions may instead incorporate UCP 600 or other applicable rules. The governing rules should be clearly stated in the instrument.
The ICC provides authoritative information about ISP98 and its application to standby credits.
5. Can an SBLC guarantee financing?
No. An SBLC doesn’t automatically guarantee that a financing institution will provide funding.
The financier must decide whether the SBLC, issuer, applicant, transaction, jurisdiction, repayment source, and proposed structure meet its requirements.
6. What is SBLC monetization?
SBLC monetization generally describes a financing arrangement where an eligible SBLC serves as credit support for funding.
Acceptance depends on the financier and the characteristics of the instrument.
7. How long does an SBLC transaction take?
There isn’t one universal timeline.
Processing can depend on the applicant’s documentation, KYC and AML requirements, transaction complexity, bank approval, instrument wording, beneficiary requirements, and banking procedures.
8. What documents are normally required?
Requirements vary, but a transaction may involve corporate registration documents, identification documents, financial statements, transaction contracts, invoices, beneficiary information, business plans, bank information, and other compliance documentation.
9. Is SBLC trade finance suitable for every business?
No.
An SBLC should serve a genuine commercial requirement. Businesses should evaluate whether an SBLC is appropriate after reviewing the underlying transaction, costs, risks, financing objective, and counterparty requirements.
Why Professional Structuring Matters
International trade finance involves several independent interests.
The buyer wants commercially workable payment terms.
The seller wants payment confidence.
The bank wants acceptable credit and compliance risk.
The financier wants a credible repayment source.
The beneficiary wants enforceable protection.
The transaction therefore needs more than an attractive financial instrument.
It needs alignment.
A properly structured SBLC transaction connects the commercial contract, financial undertaking, banking requirements, compliance framework, and financing objective.
That process can reduce avoidable misunderstandings and help each party understand what the instrument actually does.
For companies evaluating SBLC-backed trade finance, the correct starting point isn’t a promise of funding.
It’s a transaction assessment.
The Strategic Role of SBLCs in Global Trade
International commerce continues to depend on financial mechanisms that help buyers and sellers manage payment, liquidity, and counterparty risks.
The WTO has described trade finance as essential to international commerce because businesses often face a timing gap between production, shipment, delivery, and payment.
SBLCs can address one part of that challenge.
They can provide a defined bank-backed undertaking that supports an underlying commercial obligation.
Yet the quality of the outcome depends on the structure.
The issuing bank matters.
The wording matters.
The governing rules matter.
The beneficiary’s requirements matter.
The underlying contract matters.
And compliance matters.
For that reason, businesses shouldn’t approach an SBLC as a generic financial product. They should approach it as one component of a complete trade-finance structure.
Trusted External Resource for SBLC Standards
For authoritative information on standby letters of credit, businesses and advisers should consult the International Chamber of Commerce’s International Standby Practices (ISP98) resources. The ICC identifies ISP98 as a detailed framework for practitioners handling standby letters of credit.
International Chamber of Commerce — International Standby Practices ISP98
Discuss Your International Trade Finance Requirement
If your business is considering an SBLC for international trade finance, don’t start with the instrument alone.
Start with the transaction.
Identify the amount, currency, beneficiary, issuing-bank requirements, underlying contract, financing objective, jurisdiction, timeline, and expected repayment source.
Then determine whether an SBLC is appropriate.
Baili Finance (Asia) Company Limited states that it provides SBLC, bank guarantee, international trade finance, structured finance, and related financial solutions for international clients. Its published services include SBLC issuance and monetization and international trade-finance support.
If you have a genuine commercial transaction that requires payment security, credit enhancement, trade finance, or an SBLC-backed financing structure, contact Baili Finance for a transaction assessment.
Provide the essential details:
- Transaction amount
- Currency
- Applicant
- Beneficiary
- Country of transaction
- Underlying contract
- Purpose of the SBLC
- Financing requirement
- Preferred timeline
The objective isn’t simply to obtain an SBLC.
The objective is to structure a financial solution that fits the transaction.
Baili Finance — International Trade Finance & SBLC Services
Strong Summary
International trade finance with SBLC can provide businesses with a structured mechanism for managing payment obligations and counterparty risk across borders.
An SBLC can support supplier confidence, international procurement, contractual obligations, credit enhancement, and certain financing structures. However, the instrument doesn’t automatically provide cash or guarantee financing.
The most important factors include the issuing bank, beneficiary requirements, instrument wording, governing rules, transaction purpose, compliance framework, financing structure, and repayment source.
ISP98 provides a specialized framework for standby letters of credit, while UCP 600 may apply to documentary credits depending on the transaction structure.
For businesses evaluating international trade finance with SBLC, a transaction-first approach remains essential.
Define the commercial requirement.
Review the counterparties.
Verify the banking structure.
Examine the instrument.
Confirm the financing requirements.
Complete the necessary due diligence.
Then proceed with a structure that the relevant financial institutions can accept.
A well-structured SBLC isn’t about obtaining a document. It’s about creating a credible financial framework for a real commercial transaction.
READY TO STRUCTURE YOUR INTERNATIONAL TRADE FINANCE?
Your international transaction deserves a financial structure built around its actual requirements. Baili Finance Company Asia Limited provides professional support for businesses exploring international trade finance, SBLC solutions, bank guarantees, structured finance, and cross-border financial arrangements.
Whether you’re an importer, exporter, trading company, contractor, or international business, our team can help you assess your requirements and identify a suitable financing structure.
Don’t leave your transaction to uncertainty. Start with the right financial conversation.
Visit www.bailifinancelimited.com today, share your transaction requirements, and contact Baili Finance Company Asia Limited to discuss your international trade finance needs.
Your next transaction starts with the right structure.
Intermediaries/Consultants/Brokers are welcome to bring their clients 100% protected. Our brokers receive 2% commission for referral. We assist Clients and brokers in their attempt to secure funding by working on their funding requests that may require innovative financing. In complete confidence, we will work together for the benefits of all parties involved.
#InternationalTradeFinance #SBLC #TradeFinance #StandbyLetterOfCredit #SBLCFinancing #GlobalTrade #StructuredFinance