Headline: 7 Smart Strategies to Finance Your Next Property Investment
Real estate funding plays a central role in property investment, commercial development, land acquisition, and portfolio expansion. Whether you’re acquiring an income-producing building, financing a residential development, purchasing commercial property, or seeking capital for a large-scale construction project, the right funding structure can influence your cash flow, profitability, and long-term financial position.
However, securing real estate funding involves more than finding a lender. Investors and developers must assess financing options, prepare credible financial projections, understand collateral requirements, and select a funding structure that aligns with their project’s objectives.
For property investors, developers, business owners, and institutional borrowers, understanding how real estate funding works is essential to making informed decisions. This guide explains the principal property financing options, the application process, eligibility considerations, common risks, and practical strategies for presenting a property investment opportunity to potential funding partners.
Baili Finance Limited provides a starting point for businesses and investors exploring financing opportunities. The appropriate funding route will depend on the transaction, the parties involved, the available documentation, and the applicable legal and regulatory requirements.
Keywords: Real Estate Funding, Real estate financing options, Commercial real estate funding, Property development finance, Real estate investment funding, Commercial property loans, Real estate project financing, Private real estate financing, Property acquisition financing, Real estate funding requirements, How to secure real estate funding, Financing for commercial property investment, Funding for property developers, Real estate refinancing options, Real estate debt and equity financing, Funding for income-producing properties
What Is Real Estate Funding?
Real estate funding refers to the capital required to purchase, develop, renovate, refinance, or otherwise finance property-related assets and projects. Depending on the transaction, this capital may come from commercial banks, private lenders, institutional investors, investment funds, joint venture partners, or other financing sources.
The term covers several activities, including:
- Property acquisition financing: Capital used to purchase residential, commercial, industrial, or mixed-use properties.
- Real estate development finance: Funding for land acquisition, planning, construction, infrastructure, and related development expenses.
- Commercial real estate financing: Capital used to purchase or refinance offices, retail premises, warehouses, hotels, and other commercial assets.
- Property investment funding: Financing for income-producing properties and investment portfolios.
- Refinancing: Replacing an existing property loan or financing arrangement with a new facility.
- Renovation and refurbishment finance: Capital used to improve an existing property, increase its utility, or prepare it for sale or rental.
The Office of the Comptroller of the Currency’s commercial real estate lending guidance explains the main categories of commercial property lending and highlights the importance of risk management.
OCC
In practice, real estate funding isn’t a single financial product. It’s a range of possible structures, each with different costs, eligibility requirements, repayment obligations, and risk exposures.
Choosing the appropriate structure requires an assessment of the property, the borrower, the proposed transaction, and the expected source of repayment.
Why Real Estate Funding Matters to Investors and Developers
Property transactions often require substantial capital before an investor receives rental income, completes a sale, or achieves another financial return. Without suitable funding, a commercially viable project may remain unrealised.
Well-structured real estate finance can help investors allocate capital efficiently, acquire assets, manage development costs, and pursue opportunities that would otherwise exceed their available cash resources.
1. It supports property acquisition
Investors can use property acquisition financing to purchase assets without funding the entire purchase price from their own resources. Depending on the arrangement, the investor contributes equity while a lender or other capital provider supplies the balance.
This approach preserves some capital for transaction costs, maintenance, tenant improvements, and other business requirements.
2. It provides capital for development
Real estate development involves more than buying land and constructing a building. Projects may require planning approvals, professional fees, site preparation, utilities, materials, labour, insurance, and marketing.
Development finance can help cover eligible costs according to an agreed funding structure and disbursement schedule.
3. It can support portfolio expansion
Investors with existing property holdings may use financing to acquire additional assets. Nevertheless, borrowing increases financial obligations. Portfolio expansion should therefore depend on the capacity of existing and proposed assets to support the combined debt burden.
4. It can improve capital allocation
A business may prefer to preserve cash for operations instead of committing all available funds to one property transaction. Appropriate external financing can support that objective, provided the financing costs and repayment terms remain commercially sustainable.
The central principle is straightforward: capital should support a credible property strategy, not compensate for a project that lacks financial viability.
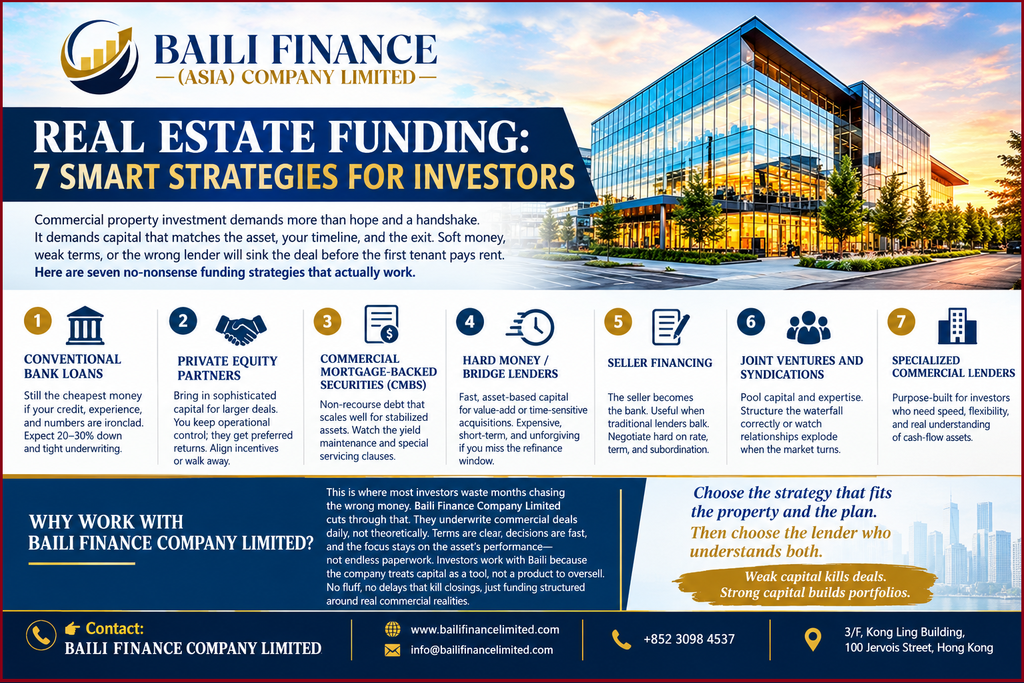
7 Smart Real Estate Funding Strategies
There is no single funding method that suits every property transaction. The most appropriate option depends on the property’s intended use, the development stage, the borrower’s financial position, the required amount, and the expected repayment source.
1. Commercial property loans
Commercial property loans can finance offices, retail premises, industrial buildings, hotels, and other income-producing or owner-occupied commercial assets. Lenders commonly assess the property valuation, borrower creditworthiness, rental income, existing liabilities, and proposed repayment arrangements.
This option may suit investors acquiring established assets with documented financial performance.
2. Real estate development finance
Development finance supports eligible construction and property development expenses. Funding may be released in stages after agreed conditions, documentation requirements, or construction milestones have been satisfied.
Developers should prepare detailed budgets, planning information, contractor agreements, construction schedules, contingency allowances, and realistic sales or rental projections.
3. Private real estate financing
Private lenders and specialist financing firms may consider transactions that require a different assessment process from conventional bank lending. Their criteria, pricing, security requirements, and funding capacity vary considerably.
Borrowers should verify the provider’s identity, authority, financial capacity, contractual terms, and proposed disbursement arrangements before committing to a transaction.
4. Joint venture property funding
A joint venture combines resources from two or more parties. One participant may contribute capital, while another provides land, development expertise, property management, or transaction sourcing.
The parties should document ownership, profit allocation, decision-making authority, additional capital obligations, exit arrangements, and dispute resolution before committing funds.
5. Mezzanine financing
Mezzanine financing can provide additional capital between senior debt and equity, subject to the structure and terms of the transaction. It may help bridge a funding gap when senior financing alone doesn’t cover the project’s capital requirements.
However, this financing can increase borrowing costs and structural complexity. Investors should assess repayment priority, intercreditor arrangements, security rights, and the effect on projected returns.
6. Equity investment
Equity investors contribute capital in exchange for an ownership interest or another agreed economic participation. Unlike conventional debt, equity doesn’t normally require fixed principal repayments under a standard loan schedule.
In return, the original property owner may need to share profits, control, or future appreciation. The legal structure must clearly define each party’s rights and obligations.
7. Property refinancing
Refinancing replaces an existing loan or financing arrangement with another facility. Investors may consider refinancing to restructure repayment terms, manage an upcoming maturity, release equity where permitted, or consolidate eligible obligations.
Before proceeding, calculate the total cost of the new facility, including fees, penalties, valuation costs, legal expenses, and any changes in interest rates or security requirements.
These options aren’t interchangeable. A construction project with no rental income may require a different funding structure from an established office building with stable tenants. Matching the funding method to the property’s financial profile is therefore a critical part of the investment process.
How to Choose the Right Real Estate Financing Option
Before approaching a financing provider, define the transaction and establish how the proposed funding will generate or preserve value.
The following factors deserve particular attention.
1. Identify the purpose of the funding
Start by specifying whether you intend to purchase land, acquire an existing building, finance construction, renovate a property, refinance an existing facility, or expand an investment portfolio.
The funding purpose determines the relevant documentation, potential financing structures, and repayment assumptions.
2. Establish the total capital requirement
Calculate the full project cost rather than relying solely on the purchase price or contractor’s initial estimate.
Include:
- Purchase price or land acquisition cost.
- Legal, valuation, and due diligence expenses.
- Planning and professional fees.
- Construction or refurbishment expenditure.
- Taxes, insurance, and applicable transaction charges.
- Interest and other financing costs.
- Working capital and contingency reserves.
A complete budget reduces the risk of a funding shortfall after the transaction begins.
3. Assess the property’s financial performance
For an income-producing property, examine rental income, vacancy assumptions, operating expenses, maintenance requirements, tenant concentration, and lease expiry dates.
For development projects, assess projected selling prices or rental income, construction costs, completion timelines, and market demand.
Forecasts should reflect available evidence rather than optimistic assumptions.
4. Compare financing costs
The stated interest rate is only one part of the cost of borrowing. Arrangement fees, commitment fees, legal costs, valuation expenses, exit fees, default interest, and early repayment charges may materially affect the total cost.
Compare financing proposals using consistent assumptions and the same projected funding period.
5. Review security and recourse
A financing provider may require a mortgage, charge over property, guarantee, assignment of certain rights, or another form of security. Some facilities provide recourse to the borrower beyond the financed property.
Understand the consequences of default, enforcement rights, restrictions on asset sales, and any obligations imposed on related entities or guarantors.
6. Test repayment capacity
Consider whether the proposed facility can be repaid from rental income, business cash flow, property sales, refinancing, or another documented source.
Where repayment depends on selling the property or securing a future loan, test the consequences of delays, lower sale prices, and tighter credit conditions.
What Lenders Look for When Assessing Real Estate Funding Applications
Although underwriting standards differ between providers and jurisdictions, several factors commonly influence a property financing decision.
| Assessment factor | What it helps establish |
|---|---|
| Property valuation | The estimated value of the asset and its suitability as security |
| Borrower financial position | The capacity to meet financial obligations |
| Loan-to-value ratio (LTV) | The proposed loan amount relative to the property’s accepted value |
| Debt-service capacity | Whether cash flow can support scheduled debt payments |
| Project feasibility | Whether development costs, timelines, and expected proceeds are credible |
| Equity contribution | The capital the borrower or partners will contribute |
| Legal due diligence | Ownership, title, encumbrances, approvals, and relevant contractual rights |
| Exit strategy | How the financing will be repaid or refinanced |
The RICS guidance on property finance and funding discusses financing sources, valuation, financial analysis, leverage, and the factors that affect property investment funding.
RICS
Understanding loan-to-value
Loan-to-value measures the loan amount against the property’s accepted valuation.
For example, suppose a property receives an accepted valuation of $5 million and the proposed loan is $3 million.
The LTV ratio is:
\[ \text{LTV}=\frac{\$3,000,000}{\$5,000,000}\times100=60\% \]
A 60% LTV means the proposed loan represents 60% of the property’s accepted value. It doesn’t guarantee approval. A provider may also consider cash flow, borrower strength, project risk, security quality, and other underwriting requirements.
Understanding debt-service coverage
For income-producing property, debt-service coverage helps assess whether the asset generates sufficient income to meet its debt obligations.
Suppose a commercial property generates annual net operating income of $600,000 and its annual debt service is $400,000.
\[ \text{DSCR}=\frac{\$600,000}{\$400,000}=1.50 \]
The resulting debt-service coverage ratio is 1.50 times. In this illustration, the property generates $1.50 in net operating income for every $1.00 of annual debt service.
Actual lender requirements vary. Investors should also test the ratio under lower-rent, higher-vacancy, increased-interest-rate, and higher-operating-cost scenarios.
Documents Required for a Real Estate Funding Application
Preparing a complete financing package can help providers evaluate a transaction more efficiently. The exact requirements depend on the funding structure, jurisdiction, property type, and applicant.
Common documents include:
Property and ownership documents
- Title documents and ownership records.
- Purchase agreement or sale contract.
- Independent valuation, where required.
- Existing mortgage and security information.
- Planning permissions, building approvals, and relevant permits.
- Leases, tenancy schedules, and rental records for occupied properties.
Financial documents
- Audited financial statements or management accounts, as applicable.
- Bank statements and evidence of available equity.
- Existing debt schedules.
- Historical rental income and operating expenses.
- Projected cash flows and financial models.
- Evidence supporting the proposed repayment strategy.
Development documents
- Construction budget and detailed cost breakdown.
- Contractor and professional service agreements.
- Project timeline and milestone schedule.
- Planning and environmental documentation, where applicable.
- Sales strategy, pre-sale agreements, or rental assumptions.
- Contingency provisions and sensitivity analysis.
Corporate and compliance documents
- Company registration records.
- Ownership and beneficial ownership information.
- Identification and verification documents.
- Board approvals and authorised signatory details.
- Information required to meet applicable anti-money-laundering and know-your-customer obligations.
Submitting a document doesn’t automatically satisfy the relevant requirement. Providers may request additional evidence, independent verification, or updated information during due diligence.
Real Estate Funding for Property Development: A Practical Process
Securing real estate development finance requires a clear explanation of the project’s commercial purpose, capital requirements, risk profile, and repayment strategy.
A developer seeking funding for a residential complex, commercial building, or mixed-use development should follow a structured process.
Step 1: Conduct a feasibility assessment
Before seeking funding, determine whether the project makes financial and operational sense.
Assess the target market, expected property demand, comparable transactions, construction costs, planning requirements, anticipated completion date, and projected revenue.
A feasibility assessment should identify the assumptions that have the greatest effect on the outcome. These may include interest rates, construction inflation, rental growth, occupancy, sales prices, and completion delays.
Step 2: Prepare a development appraisal
A development appraisal brings together the expected costs, revenue, funding requirements, and projected financial results.
For example, a developer might estimate the completed property’s value, deduct construction costs and other expenses, and then evaluate whether the remaining amount supports the proposed investment.
However, a positive appraisal doesn’t automatically establish that a project can secure funding. The provider must also consider the borrower’s contribution, timing of cash flows, security, and repayment capacity.
Step 3: Determine the capital structure
A project’s capital structure describes how the required funding will be divided between debt, equity, and other financing sources.
A developer may contribute personal or corporate capital, obtain senior debt, and seek additional equity or subordinated financing where appropriate.
Each component has different implications for ownership, repayment priority, financing costs, and control. These implications should be modelled before the parties commit to a structure.
Step 4: Present the funding proposal
A professional funding proposal should explain:
- The amount of capital required.
- The intended use of the funds.
- The property and its legal ownership status.
- The applicant’s relevant financial position and experience.
- The project’s budget and implementation schedule.
- The proposed funding structure.
- The expected source and timing of repayment.
- The principal risks and proposed mitigation measures.
The objective is to give a potential financing provider sufficient information to evaluate the transaction. Avoid unsupported claims about profitability, guaranteed repayment, or future property values.
Step 5: Complete due diligence and documentation
If a provider decides to proceed, the transaction may require valuation, legal review, financial verification, background checks, and other due diligence.
The parties should agree on the conditions that must be satisfied before funds become available. These may include executed agreements, registered security, planning approvals, equity contributions, insurance, or other transaction-specific requirements.
Step 6: Manage the funding after completion
Funding management continues after the facility closes.
Developers should monitor expenditure against the approved budget, maintain accurate financial records, report material changes, and manage construction or leasing milestones.
Where funding is released in stages, the borrower should understand the conditions for each drawdown and allow sufficient time to meet them.
A funding strategy is only as reliable as its execution. Financial discipline throughout the project helps identify problems early and supports informed decisions.
Real Estate Funding Case Study: A Commercial Property Acquisition
The following case study is an illustrative scenario created to explain how property funding decisions work. It doesn’t represent a verified transaction completed by Baili Finance Limited or a named client.
The investment opportunity
A property investment company identifies a commercial building suitable for long-term rental. The building has existing tenants, but the company expects to improve occupancy and complete targeted renovations.
The purchase price is $4 million. The investor has $1.5 million available for the acquisition and wants to finance the remaining purchase price.
However, the acquisition also requires capital for transaction costs, initial improvements, and working capital.
The proposed funding structure
The investor prepares the following preliminary budget.
| Item | Illustrative amount |
|---|---|
| Property purchase price | $4,000,000 |
| Legal and transaction costs | $100,000 |
| Initial refurbishment | $250,000 |
| Working capital reserve | $150,000 |
| Total project budget | $4,500,000 |
| Investor’s proposed contribution | $1,500,000 |
| Proposed financing requirement | $3,000,000 |
The proposed funding requirement is $3 million, assuming the investor contributes $1.5 million toward the total $4.5 million budget.
However, the investor must confirm that the contribution is available, that the financing structure covers the intended expenses, and that the provider accepts the proposed allocation of funds.
The $3 million facility represents 75% of the $4 million purchase price. This calculation is not necessarily the lender’s official LTV, because the lender may use a different accepted valuation or calculate LTV according to the specific facility and its security arrangements.
Evaluating the income
Assume the building generates projected annual net operating income of $360,000 after property operating expenses but before financing costs and income taxes.
If annual debt service under the proposed facility amounts to $270,000, the projected debt-service coverage ratio would be:
\[ \text{DSCR}=\frac{\$360,000}{\$270,000}=1.33 \]
Under these assumptions, the property generates approximately $1.33 in annual net operating income for each $1.00 of annual debt service.
The investor shouldn’t rely on this figure alone. The next step is to assess how the property would perform if occupancy declined, renovation costs increased, or interest rates rose.
Testing the downside
Suppose net operating income falls by 20% to $288,000 while annual debt service remains at $270,000.
The revised coverage ratio becomes:
\[ \text{DSCR}=\frac{\$288,000}{\$270,000}\approx1.07 \]
The property would still generate income above annual debt service in this simplified example, but the margin would be considerably narrower.
A further decline in income or an increase in financing costs could eliminate that margin. The investor should therefore examine the availability of reserves, lease renewal risks, tenant concentration, refinancing conditions, and alternative repayment options.
The funding decision
A responsible assessment would examine the accepted property valuation, the investor’s equity contribution, lease documentation, refurbishment budget, legal title, projected cash flow, and proposed repayment strategy.
The financing provider would then determine whether the transaction meets its requirements and, if so, on what terms.
The case study illustrates a central lesson: the ability to purchase a property doesn’t automatically establish the ability to finance and operate it successfully. A complete funding plan must account for acquisition costs, ongoing obligations, cash flow volatility, and the eventual repayment of the financing.
Real-World Example: Financing an Income-Producing Property
Consider a hypothetical real estate investor acquiring a warehouse leased to a distribution company under a multi-year agreement.
The investor expects to receive rental income and use that income to meet operating expenses and debt payments.
Before applying for commercial property financing, the investor reviews the lease, verifies the tenant’s payment history, obtains a property valuation, and estimates maintenance expenditure. The investor also examines the lease’s expiry date and the cost of finding a replacement tenant if the existing tenant leaves.
The financing proposal includes the purchase agreement, evidence of available equity, property information, historical operating expenses, projected income, and an explanation of the intended repayment strategy.
During due diligence, the financing provider identifies that the tenant’s lease expires earlier than the investor initially expected. The investor revises the financial model to include a potential vacancy period and leasing costs.
This adjustment may reduce projected income, but it gives the parties a more realistic basis for evaluating the transaction.
The example demonstrates why commercial real estate funding decisions should account for tenant quality, lease duration, operating costs, and future capital expenditure. Property valuation alone doesn’t provide a complete picture of repayment capacity.
Common Real Estate Funding Mistakes to Avoid
Even a promising property transaction can encounter financial difficulties when the funding strategy overlooks important risks.
Underestimating the total project cost
Purchase prices and construction contracts don’t always capture every expense. Professional fees, insurance, taxes, financing charges, utility connections, delays, and unexpected repairs may increase the capital requirement.
Prepare a comprehensive budget and include a contingency appropriate to the project’s risk profile.
Relying on optimistic income projections
A financial model that assumes full occupancy, immediate rent collection, or uninterrupted construction may overstate the project’s capacity to repay debt.
Use defensible assumptions and test alternative outcomes.
Ignoring the maturity date
Some property loans have a defined maturity date and require a substantial repayment or refinancing at that point.
Borrowers should begin preparing for repayment well before maturity. A future refinancing facility isn’t guaranteed, even if the property has performed as expected.
Accepting unclear financing terms
Borrowers should understand all fees, interest calculations, default provisions, drawdown conditions, security obligations, and repayment requirements before signing.
Seek independent legal and financial advice where appropriate.
Treating funding discussions as confirmed financing
An initial discussion, expression of interest, indicative term sheet, or preliminary assessment doesn’t necessarily constitute a binding commitment to provide funds.
Verify the status of each proposal and identify the conditions that remain outstanding.
Failing to verify a financing provider
Before paying any fees or transferring funds, verify the provider’s legal identity, relevant authorisations, track record, financial capacity, and contractual arrangements.
Be particularly cautious of claims that financing is guaranteed regardless of the applicant’s circumstances or that payment of an upfront fee automatically secures a facility.
How Baili Finance Limited Fits Into Your Funding Research
Investors and developers exploring real estate funding need a clear understanding of their capital requirements and the financing arrangements available for their specific transactions.
Baili Finance Limited’s website, www.bailifinancelimited.com, is the appropriate starting point for readers who want to learn more about the company and make an enquiry.
Before approaching any financing provider, prepare a concise overview of the project, the required amount, the intended use of funds, the proposed repayment source, and the supporting documentation.
When making an enquiry, ask clear questions about the provider’s role, the relevant financing options, eligibility requirements, due diligence, applicable fees, security requirements, and expected process.
The company’s actual services, eligibility criteria, and ability to support a particular transaction should be confirmed directly. No specific funding outcome, approval, rate, or completion date should be assumed before the relevant assessment.
For property investors, a well-prepared enquiry is more useful than a general request for capital because it gives the parties a defined transaction to evaluate.
External source:
Office of the Comptroller of the Currency — Commercial Real Estate Lending
This resource supports the article’s discussion of commercial real estate lending and risk management.
Frequently Asked Questions About Real Estate Funding
1. What is real estate funding?
Real estate funding is the capital used to purchase, develop, renovate, refinance, or invest in property. Depending on the transaction, funding may come from commercial banks, private lenders, institutional investors, equity partners, or other capital providers. The appropriate source depends on the property’s purpose, the borrower’s financial position, the proposed security, and the expected repayment strategy.
2. How can I get funding for a real estate project?
Start by defining the project, calculating the total capital requirement, and preparing a credible financial model. Gather property ownership documents, valuation information, financial statements, project budgets, and evidence of your equity contribution. Identify suitable financing providers, compare their requirements, and submit a documented proposal. Funding remains subject to the provider’s assessment, due diligence, and contractual conditions.
3. What types of real estate funding are available?
Common options include commercial property loans, development finance, private lending, joint venture financing, mezzanine financing, equity investment, and refinancing. Each option has different costs, repayment obligations, security arrangements, and ownership implications. A suitable structure should reflect the project’s stage, expected cash flow, risk profile, and investment objectives.
4. Can I obtain real estate funding without owning the property already?
Potentially, yes. Some acquisition and development financing arrangements allow a borrower to seek funding before completing a property purchase. However, the transaction may require an executed purchase agreement, an acceptable property valuation, a defined equity contribution, legal due diligence, and evidence of repayment capacity. Approval isn’t guaranteed, and requirements vary by provider and jurisdiction.
5. How much real estate funding can I obtain?
There is no universal funding amount. A provider may consider the property’s accepted valuation, the borrower’s financial position, the proposed loan-to-value ratio, projected income, existing liabilities, available equity, and the purpose of the facility. For development projects, the budget, completion risks, expected sales or rental income, and exit strategy may also affect the assessment.
6. What documents are required for property financing?
Requirements vary, but applicants commonly provide property title records, purchase agreements, valuation reports, financial statements, bank statements, project budgets, cash flow projections, corporate registration documents, and information about existing debt. Development applications may also require planning permissions, construction contracts, cost schedules, and project timelines.
7. Is commercial real estate funding different from residential property financing?
Yes. Commercial real estate financing often places significant emphasis on rental income, tenant quality, lease terms, operating expenses, and the property’s ability to support debt payments. Residential property financing may place greater emphasis on personal income, credit history, household liabilities, and property value, depending on the product and jurisdiction. Investment residential property can also require detailed rental cash flow analysis.
8. What is the difference between real estate debt and equity financing?
Debt financing involves borrowing capital under agreed repayment terms. The borrower generally pays interest and repays principal according to the facility agreement. Equity financing involves contributing or raising capital in exchange for an ownership interest or another agreed participation in the investment. Debt creates repayment obligations, while equity can dilute ownership and influence decision-making.
9. How long does it take to secure real estate funding?
The timeframe depends on the transaction’s complexity, the financing provider, document completeness, valuation, legal due diligence, regulatory requirements, and the conditions that must be satisfied before funds can be released. Straightforward transactions may progress faster than large development projects or cross-border arrangements. Applicants should request a realistic timetable and avoid making irreversible commitments before financing conditions are sufficiently clear.
10. What risks should investors consider before accepting property funding?
Investors should assess interest-rate changes, refinancing risk, construction delays, cost overruns, tenant vacancies, falling property values, reduced rental income, currency exposure where relevant, and the possibility of default. They should also review guarantees, security enforcement provisions, fees, and repayment deadlines. Independent legal and financial advice can help clarify the consequences of a proposed financing arrangement.
Final Thoughts: Build Your Property Strategy Around the Right Funding
Real estate funding can support property acquisition, commercial investment, development, refurbishment, and portfolio expansion. However, a successful financing strategy requires more than identifying a source of capital.
Investors must understand the total project cost, assess realistic cash flows, compare funding structures, prepare accurate documentation, and plan for repayment under both expected and adverse conditions.
Whether you’re purchasing a commercial building, developing residential units, financing a warehouse, or evaluating a property portfolio, the right approach begins with a clear investment objective and a credible financial plan.
Before pursuing your next property opportunity, establish how much capital you need, how you’ll use it, what security you can provide, and how you intend to repay it. These fundamentals help you evaluate financing proposals and identify structures that fit your circumstances.
Baili Finance Limited invites property investors, developers, and businesses to explore the information available on its website and make an enquiry about their financing requirements.
READY TO SECURE FUNDING FOR YOUR NEXT PROPERTY PROJECT?
Your next real estate investment deserves a clear funding strategy.
Whether you’re acquiring commercial property, financing a development, expanding your property portfolio, or exploring funding for a major real estate transaction, the right financing approach starts with understanding your objectives, capital requirements, and repayment strategy.
Don’t let uncertainty about financing delay your next business decision. Take the initiative, define your funding requirements, and explore the options available for your transaction.
Baili Finance Limited invites property investors, developers, and businesses to make an enquiry about their real estate funding requirements.
Visit: www.bailifinancelimited.com to learn more about our company and contact us to discuss your proposed transaction.
When contacting us, be prepared to share:
- Funding required: The amount of capital your project needs.
- Project details: The property type, location, and purpose of the transaction.
- Funding purpose: Whether you intend to acquire, develop, renovate, or refinance a property.
- Financial position: Your available equity, existing obligations, and supporting documentation.
- Repayment strategy: Your proposed source of repayment and expected timeline.
The more clearly you define your requirements, the more effectively your enquiry can communicate the transaction you want to pursue.
TAKE THE NEXT STEP TOWARDS YOUR PROPERTY FUNDING GOALS.
Visit:Baili Finance Limited today and submit your enquiry. Start the conversation, outline your funding requirements, and explore whether an appropriate financing arrangement may be available for your project.
All financing enquiries remain subject to assessment, due diligence, applicable requirements, and agreed terms. Submission of an enquiry does not guarantee funding or approval..
Intermediaries/Consultants/Brokers are welcome to bring their clients 100% protected. Our brokers receive 2% commission for referral. We assist Clients and brokers in their attempt to secure funding by working on their funding requests that may require innovative financing. In complete confidence, we will work together for the benefits of all parties involved.
#RealEstateFunding #PropertyFinance #CommercialRealEstate #RealEstateInvestment #PropertyDevelopment #RealEstateInvestors #DevelopmentFinance #PropertyInvestment